Section 194R and Free Products: The Tax Rule Most Indian Brands Get Wrong
10 min read · Influverse · Ahmedabad
Section 194R and Free Products: The Tax Rule Most Indian Brands Get Wrong
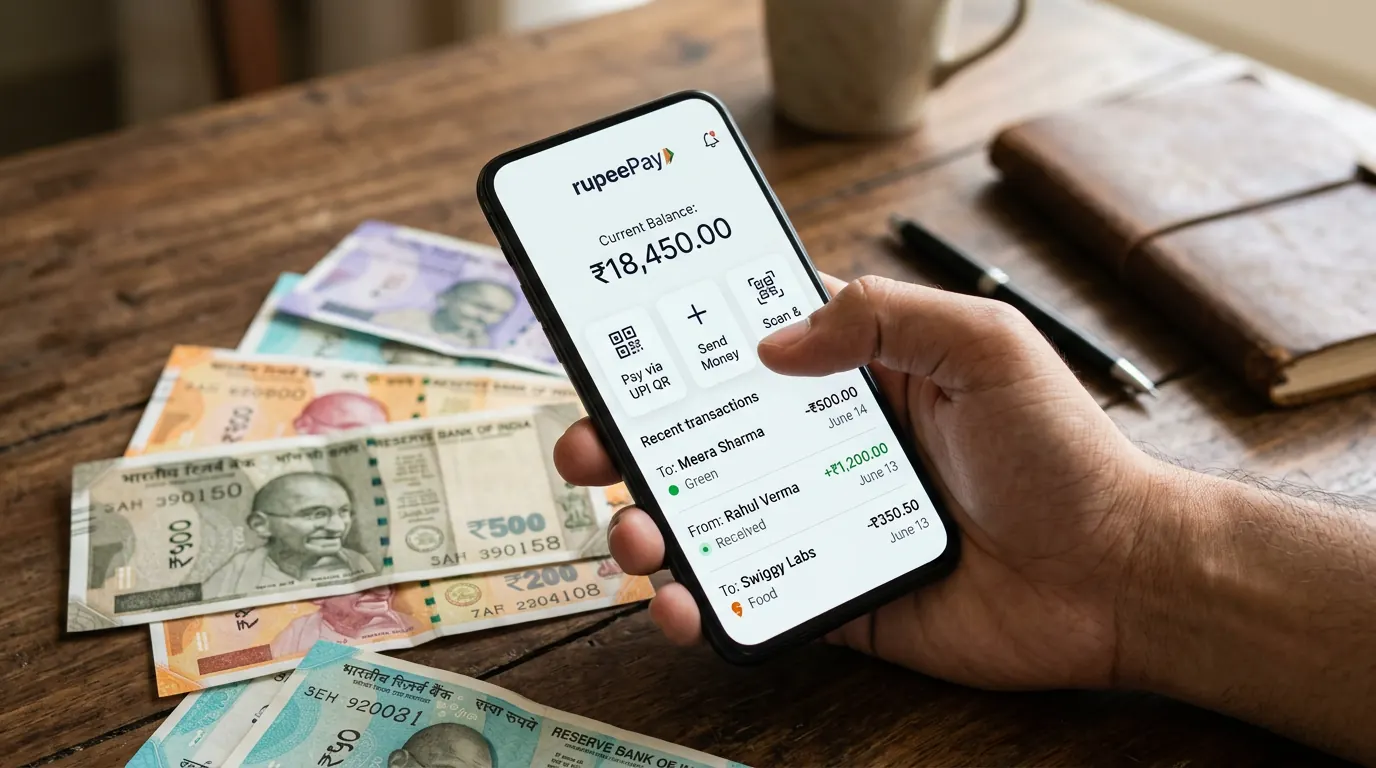
Influencer seeding runs on generosity: hampers, phones, hotel stays, sent with no invoice and no paperwork. Since July 2022, the Income Tax Department has run on Section 194R — which treats those gifts as taxable benefits and makes your brand responsible for the TDS.
Most Indian brands are still non-compliant on 194R, mostly out of ignorance. This guide explains the rule, the exemptions, and the operational systems that let a seeding programme survive it.
What 194R actually says
Any person providing a benefit or perquisite exceeding ₹20,000 in aggregate per recipient per financial year must deduct 10% TDS before providing it. 'Benefit' explicitly includes free products, and CBDT clarifications confirmed it covers influencer gifting — even when there is no formal contract.
The threshold is per creator, per year, across everything you send. Three ₹8,000 hampers to the same creator cross it. Your seeding tracker needs an annual value column per creator, not just a dispatch list.
The returnable-unit exemption
If the product is loaned and returned after the campaign, it is not a benefit — no 194R. This is why electronics and luxury brands now write 'review unit, to be returned within 30 days' into every seeding note, and why return logistics have become part of PR ops.
Be honest about it: if there is no real intent or mechanism to collect the product back, it is a gift regardless of what the note says. The exemption survives scrutiny only when returns actually happen.
Who bears the tax — three working models
Model one: the creator pays the TDS amount to the brand before dispatch (cleanest, but a hard conversation for a 'gift'). Model two: the brand bears the tax and grosses up — a ₹50,000 gift effectively costs ₹55,555. Model three: keep per-creator annual gifting under ₹20,000 and the rule never fires.
Most sophisticated Indian programmes in 2026 run a hybrid: sub-threshold seeding for nano creators, gross-up for high-value gifts to priority creators, and returnable units for expensive products.
Related deep dive: Exclusivity Clauses in Indian Creator Contracts: How Long, How Wide, How Much Extra.
Operational compliance: the boring system that saves you
Collect PAN at onboarding — without it, TDS is 20% and the conversation is worse. Maintain a per-creator annual gift ledger. Issue the TDS certificate (Form 16A) so the creator can claim the credit; creators who discover unreported 194R deductions in their Form 26AS without a certificate become former partners.
Train the marketing team last, not first. They are the ones who decide to 'just send one more hamper' in week 50 of the year, crossing a threshold nobody tracked.
The Bottom Line
194R did not kill influencer gifting — it professionalised it. Track value per creator, choose your tax-bearing model, and put return language on expensive units.
General information, not tax advice — confirm with your CA. For the cash side of creator payments, see our TDS sections explainer and payment terms framework.
Frequently asked questions
What 194R actually says?+
Any person providing a benefit or perquisite exceeding ₹20,000 in aggregate per recipient per financial year must deduct 10% TDS before providing it. 'Benefit' explicitly includes free products, and CBDT clarifications confirmed it covers influencer gifting — even when there is no formal contract.
What about: The returnable-unit exemption?+
If the product is loaned and returned after the campaign, it is not a benefit — no 194R. This is why electronics and luxury brands now write 'review unit, to be returned within 30 days' into every seeding note, and why return logistics have become part of PR ops.
Who bears the tax — three working models?+
Model one: the creator pays the TDS amount to the brand before dispatch (cleanest, but a hard conversation for a 'gift'). Model two: the brand bears the tax and grosses up — a ₹50,000 gift effectively costs ₹55,555. Model three: keep per-creator annual gifting under ₹20,000 and the rule never fires.
What about: Operational compliance: the boring system that saves you?+
Collect PAN at onboarding — without it, TDS is 20% and the conversation is worse. Maintain a per-creator annual gift ledger. Issue the TDS certificate (Form 16A) so the creator can claim the credit; creators who discover unreported 194R deductions in their Form 26AS without a certificate become former partners.
Keep reading
 Costs, ROI & Performance
- Costs, ROI & Performance
- Strategy & Agency Guides
How Influencer Whitelisting Improves Meta Ad Performance
- Costs, ROI & Performance
- Strategy & Agency Guides
Creator-Led Ads vs Brand-Created Ads: Which Converts Better?
- Costs, ROI & Performance
- Strategy & Agency Guides
How Influencer Marketing Reduces Customer Acquisition Cost
- Costs, ROI & Performance
- Strategy & Agency Guides
How Influencer Marketing Supports Performance Marketing Campaigns
 Strategy & Agency Guides
- Strategy & Agency Guides
- Contracts, Tax & Payments
How to Choose Influencers Based on Audience Quality Instead of Followers
 Strategy & Agency Guides
- Strategy & Agency Guides
- Costs, ROI & Performance
- Creators, Platforms & Media